You may have more homes to choose from, but buying one still depends on your budget
Australian property prices have fallen in recent months, and more homes are sitting on the market. But lower prices do not automatically make it easier for you to buy. You still need a deposit, a loan your lender will approve and enough income to manage the repayments and other costs.
Cotality’s September Home Value Index recorded a 1.1% fall in national dwelling values, the sixth monthly decline in a row. Values were 5.2% below their March peak and 3% lower than at the end of 2025.
The national result hides different local markets. From the end of 2025 to September, values fell 8.2% in Sydney and 7% in Melbourne. They rose 1.5% in Perth and 6.4% in Darwin.
More homes are staying on the market for longer
In September, total advertised housing stock across the combined capital cities was 23.1% higher than a year earlier. Yet new listings were 9.2% lower. Cotality says homes were taking longer to sell, so properties accumulated on the market even as fewer new ones came up for sale.
Cotality also estimated that the number of homes sold nationally over the previous three months was 19.1% lower than a year earlier. That is a measure of completed sales, not the number of buyers looking.
Together, these figures describe a slower market: more advertised homes remain available, but fewer transactions are taking place. You may have more properties to consider and more time to weigh them up. The figures alone cannot tell us why individual buyers have delayed or ruled out a purchase.
A lower price can reduce your deposit and loan
A lower price may bring your deposit target closer. For example, if a property falls in value from $800,000 to $776,000, a 20% deposit falls from $160,000 to $155,200. You would need $4,800 less for the deposit and borrow $19,200 less.
This is an illustration of a 3% price fall, matching the national change from the end of 2025 to September. It does not mean every property has fallen by 3%. Prices have moved differently between cities, suburbs and property types.
You also need to budget for costs such as stamp duty, conveyancing and inspections. A smaller deposit target does not cover those expenses.
Higher rates can limit what you can borrow
The RBA’s latest published lending-rate data shows that the average rate on new owner-occupier principal-and-interest loans rose from 5.42% in December 2025 to 6.15% in August 2026. These averages include fixed and variable loans; your lender’s rate may differ.
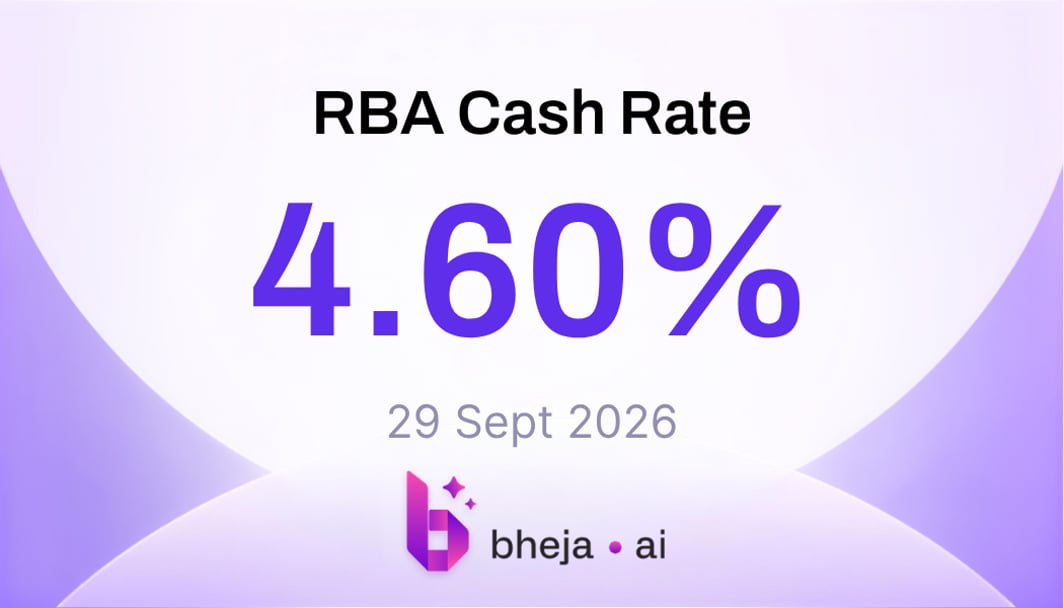
The RBA has since raised the cash rate to 4.60%. The four major banks announced 0.25 percentage point increases to their variable home loan rates. For a $500,000 variable loan, a 0.25 per cent increase can add about $79 a month to repayments on a 30-year principal-and-interest loan. Your change will depend on your rate, balance and remaining loan term.
A higher rate can also reduce the amount a lender will approve. APRA requires banks to assess whether you could manage repayments at least 3 percentage points above your loan rate. Lenders also consider your income, living expenses and other debts.
That means a lower property price may reduce the loan you need, while a higher assessment rate may reduce the loan you qualify for. You need to check both numbers.
Your household budget matters after settlement too
A lender’s approval does not show how comfortable the repayments will feel in your household budget.
In its October 2026 Financial Stability Review, the RBA reported that real household disposable income per person fell slightly in the first half of the year. Higher inflation and interest rates contributed to the decline.
The RBA estimated that around 2% of variable-rate owner-occupier borrowers did not have enough income to cover scheduled mortgage repayments and essential expenses. Lower-income borrowers faced greater pressure. Some cut spending, traded down, sold assets or worked extra hours. Most borrowers still had enough income to meet repayments and essential costs, and many held savings buffers.
The review describes existing borrowers, not prospective buyers. But it shows why you should leave room in your budget for costs beyond the mortgage, including utilities, insurance, rates, maintenance and everyday expenses.
How to work out what you can afford
Start with your household budget. Work out how much you could put towards a mortgage each month after covering regular expenses, other debts and savings for unexpected costs. Include housing costs such as council rates, insurance, utilities and maintenance.
Then check the upfront costs. Set aside enough for your deposit and buying costs, and consider how much savings you would have left after settlement.
Ask your lender or broker how much you may be able to borrow at current rates. Compare the estimated repayment with the amount your budget can manage, then check how it would change if rates rose again. A lender’s maximum borrowing estimate may be higher than the repayment you feel comfortable making.
Use your deposit, borrowing estimate and monthly budget together to work out what is affordable for you. Revisit the figures if your income, expenses or interest rate changes.