The short answer:
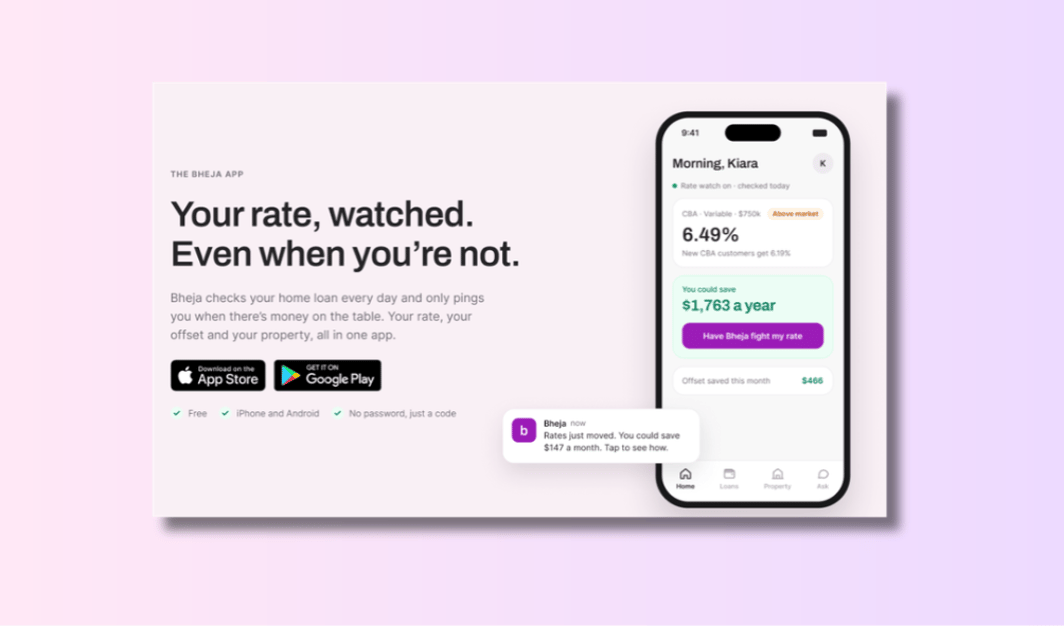
Bheja.ai looks after your home loan for its whole life, not just on settlement day. Connect your loan through Open Banking, and you can see, in your own numbers, whether you are paying more than the market and whether your offset is doing its job. No expert is needed to start, and no credit check.
When there is money to save, Bheja.ai helps you ask your current lender for a better rate first, and refinance only if that makes sense. A licensed mortgage broker is there when you want one. It costs you nothing.
Why it matters now
The Reserve Bank lifted the cash rate to 4.85% on 3 November 2026, its fifth rise this year and the highest level since 2008. Major banks passed the full 0.25% on to variable borrowers from 13 November (Broker News). That puts two quiet costs under a brighter light.
The loyalty gap. Lenders often save their sharpest rates for new customers. Canstar estimated the average owner-occupier variable rate at about 6.74% after this hike, while 40+ lenders offered under 6.50%. If you have not checked your rate recently, you may be on the wrong side of that gap. Run the free health check to see where you stand.
Offsets that do not work. In July 2026 ASIC reviewed eight banks and found weaknesses in how all of them set up and monitor offset accounts (ASIC REP 837). Banks paid over $55 million in compensation for offset failures reported between September 2023 and August 2025 (ASIC). The most common problem was an offset that was opened but never linked to the loan.
Not sure about yours? The offset account tracker checks whether your offset is linked and saving you interest.
Six things that make Bheja.ai different
- It is about your loan, not an average borrower. Bheja.ai reads your actual rate, balance and loan structure through Open Banking (the Consumer Data Right). It then compares them with current rates for your loan size and loan-to-value ratio (LVR), using published product data from 100+ lenders.
- It shows the dollar figure. Instead of a list of rates, you see what the difference is worth to you each year and over five years. That makes the choice to act, or not, an easy one.
- You can try it yourself, first. The health check takes about 60 seconds, has no impact on your credit score, and does not ask you to talk to anyone. Bring in a broker only when you are ready.
- It checks your offset is actually working. The offset account tracker looks at whether your offset is linked to your loan and reducing the interest you pay. After ASIC's findings, that is worth checking, even if your rate is already sharp.
- It keeps watching after you settle. Rates move and lenders reprice. Monitor your home loan and Bheja.ai keeps benchmarking it against the market, letting you know when a gap opens.
- It acts for you, not just alerts you. When your rate drifts, Bheja.ai can prepare a repricing request to your current lender's retention team, with your authority. If staying does not make sense, its licensed broker can handle a full refinance across 100+ lenders.
The idea is simple: a home loan is a 25- or 30-year relationship, so it deserves care for 25 or 30 years, not a one-off transaction.
What the two quiet costs add up to
A rate 0.50% above the market and an unlinked offset together cost this borrower about $33,000 in interest over five years. Each problem on its own costs roughly $15,000 to $19,000.
The example: a $750,000 owner-occupier variable loan, 25 years remaining, principal and interest, monthly repayments, with $40,000 sitting in an offset account. 6.74% is Canstar's estimated post-November average; 6.24% is a rate inside the range 40+ lenders were offering.
Reading across: fixing the offset alone (A to B) saves about $16,000. Closing the rate gap alone (A to C) saves about $18,700. Fixing both saves about $33,300.
Want your own numbers instead of an example? The free health check runs this comparison on your actual loan.
Illustrative only. Assumes rates and the offset balance stay constant for 60 months. Your result depends on your LVR, credit profile, lender eligibility, fees and switching costs. A refinance may involve discharge and government fees.
Where Bheja.ai fits
Australians have good options for finding a home loan. Bheja.ai is built for what comes after: keeping that loan sharp for years. The table below shows what each type of service does well, and what Bheja.ai adds.
Many people use more than one of these. Bheja.ai works alongside them: it is the part that keeps watching your loan once the paperwork is done.
How it works
- Run the health check. Enter a few details or connect your loan through Open Banking. The health check takes about 60 seconds and does not touch your credit file.
- See your savings. Bheja.ai compares your rate with current rates for your LVR and shows the difference in dollars. The offset account tracker checks that your offset is linked and working.
- Choose what to do. Stay put, ask your lender to reprice, or explore a refinance. You decide; nothing happens without your say-so. Questions along the way? Ask Bheja or book a time with a human expert.
- Let Bheja.ai ask your lender. With your written authority, Bheja.ai sends a repricing request to your lender's retention team.
- Refinance if it is worth it. If your lender will not move, a licensed broker can compare 100+ lenders and handle the switch, including the costs of moving.
- Stay covered. Monitor your home loan, and Bheja.ai tells you when your rate or offset needs attention.
Licensing and how Bheja.ai is paid
Bheja.ai is both a technology platform and a licensed mortgage broking service. Credit services are provided by Bheja Group Pty Ltd, Corporate Credit Representative 570637 of Purple Circle Financial Services Pty Ltd (Australian Credit Licence 486112). Complaints that are not resolved directly can go to the Australian Financial Complaints Authority (AFCA member 115819). The service is led by licensed mortgage broker and fintech CTO Pravin Mahajan.
Bheja.ai charges borrowers nothing. Like other Australian brokers, it receives upfront and trail commissions from the lender only if you take out or refinance a loan through it. Lenders cannot pay to change their position in Bheja.ai's comparisons, and as a broker, Bheja.ai must act in your best interests under the Best Interests Duty. Commission details are in our Credit Guide.
Frequently asked questions
Comparison sites are great for researching the market. Bheja.ai starts from your own loan: it reads your actual rate and balance through Open Banking, compares them with rates for your LVR, and shows what the gap is worth in dollars. It then keeps checking over time.